 ElectrifiedExperts
Why is EV insurance so expensive? Because the cars are worth a lot, they carry a big and costly battery pack, and even a moderate crash can send repair bills past the point where an insurer would rather total the car than fix it. That risk gets baked into your premium. The effect is worst on Teslas, where parts, body-shop bottlenecks, and rising loss histories stack on top of each other. The quote shock is real, but it is not fixed in stone, and the model you pick changes the number a lot.
If you just got a quote that made you close the browser tab, you are not imagining it. Owners on r/electricvehicles trade these numbers constantly, and some of them are brutal.
Why is EV insurance so expensive compared to a gas car?
EV insurance is expensive because the vehicle values are high, the battery pack is the single priciest component in the car, and structural or sensor damage that a gas car would shrug off can total an EV instead. Insurers price for the cost of a claim, and on many EVs a fender-bender is an expensive claim. Teslas get hit hardest of all.
Here is the short version of what actually drives the premium up:
- The battery pack is the car. On many EVs the pack sits low in the floor, and damage to it can run into five figures. If the pack is compromised, the car is often written off.
- Sensors and cameras live in the bumpers. A low-speed tap that used to mean a scuffed cover now means replacing and recalibrating driver-assist hardware, which is not cheap.
- Moderate hits total the car. When the repair estimate climbs past a chunk of the car’s value, the insurer pays out the whole car instead of fixing it. That drives up loss costs, and loss costs drive up premiums.
- Tesla-specific parts and labor. Body shops certified to work on Teslas are limited in many areas, so parts wait times and labor rates run high.
- High vehicle values. A more valuable car costs more to replace, full stop.
- Loss history. Some models simply have worse claims records, and insurers price the model, not just the driver.
Kelley Blue Book has reported that Tesla insurance costs have been rising fast, which lines up with what owners are seeing at renewal. You can read their writeup here.
How bad are the quotes, really?
Bad enough that people are naming threads after it. One was literally titled “Insurance is Killing EVs.” In that thread, an owner said they were quoted:
“GEICO for $880/m to fully cover the USED Tesla”
That was for a used 2020 Model 3, against roughly $240 a month to cover a Mercedes GLB. Same driver, wildly different bill. You can see the thread on r/electricvehicles.
Here is a detail that catches a lot of shoppers off guard: buying used does not always save you on insurance. One owner comparing quotes on the same Progressive policy found a used 2023 Model Y came in at:
“$1,250/month”
while a brand-new 2025 was:
“$960/month”
The newer car was cheaper to insure than the older one, and that post pulled 59 upvotes from people who had run into the same thing. It’s on r/electricvehicles. Newer models can carry better safety hardware and repair pathways, and insurers weigh that.
Location and driver history pile on too. A new Washington driver shopping a Model 3 reported State Farm at:
“$609/month”
and, from the same search:
“Geico at $5,080 for 6 months”
That Geico figure works out to about $847 a month. Same car, same person, and the gap between carriers is enormous. Their post is here.
Why does minor damage cost so much on an EV?
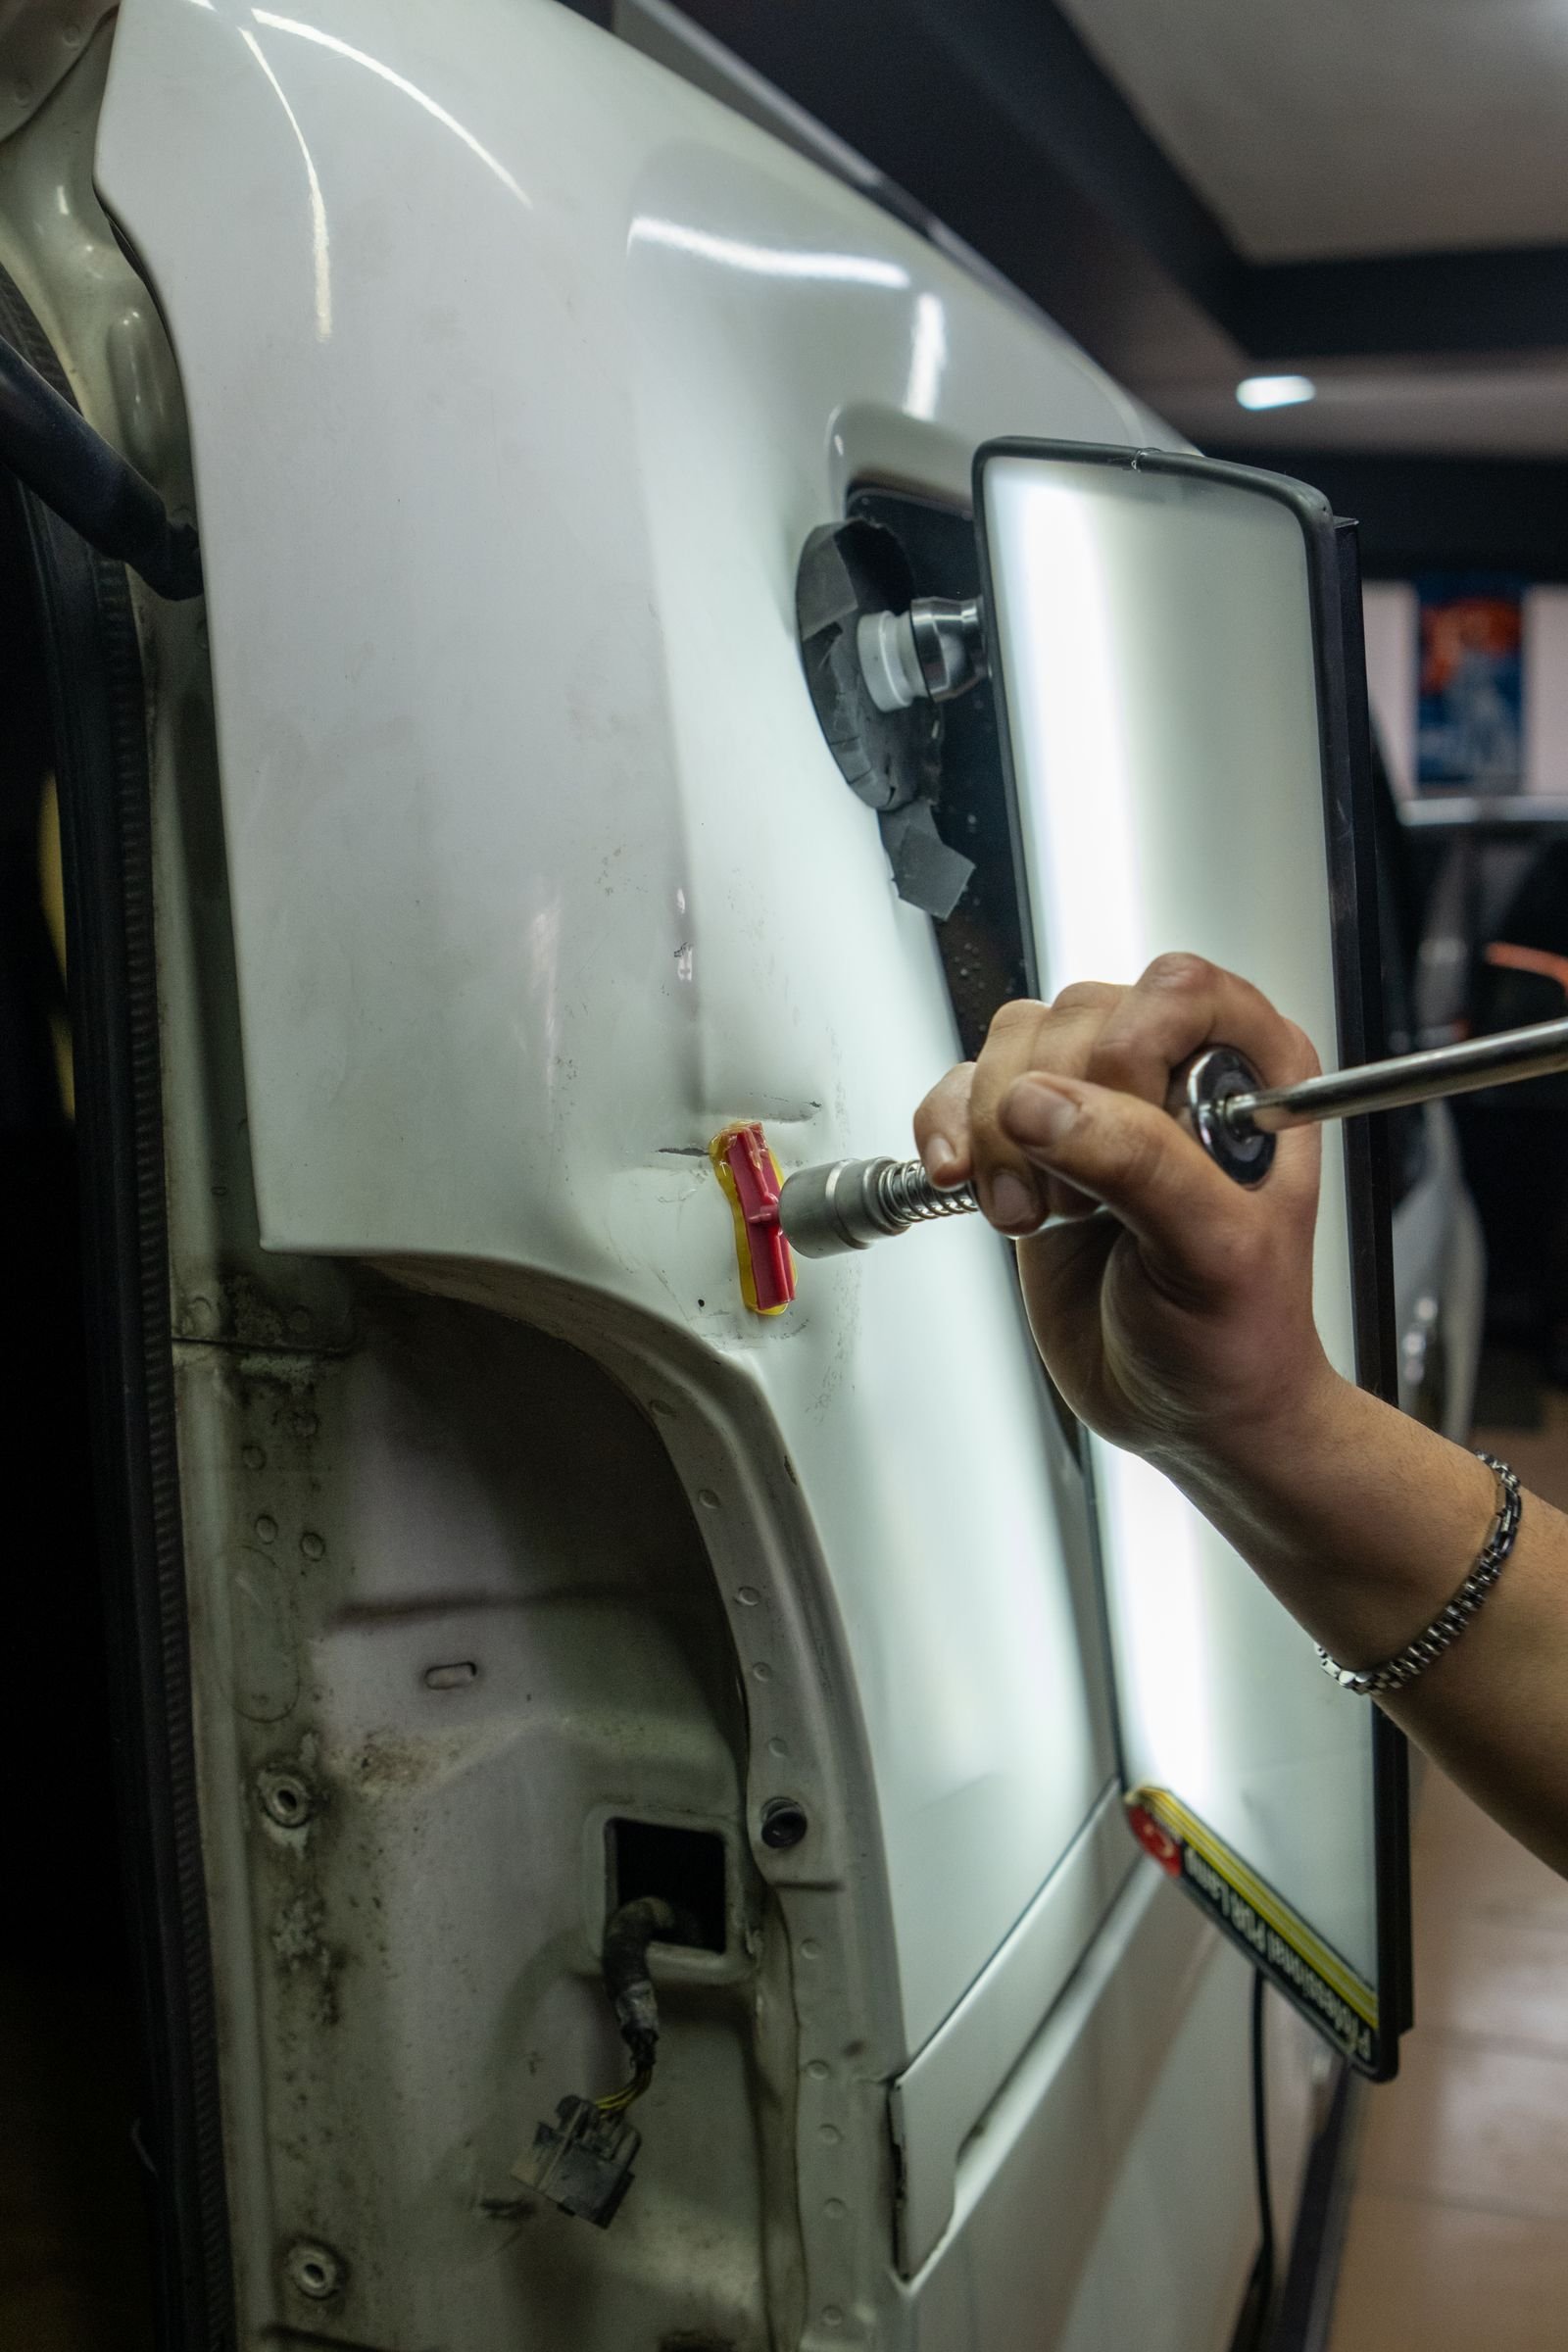
This is the part that surprises people, and it explains a lot of the premium. On a lot of EVs, damage that looks minor from the outside is expensive underneath, and once the estimate climbs high enough the insurer totals the car rather than repairing it.
One owner’s 2020 Nissan Leaf hit a deer. Not a highway pileup, a deer. Here is what happened:
“Repair shop quoted $13k and had not even taken the front apart yet”
The car was totaled before the shop had fully opened up the front end. That story is on r/electricvehicles. When a single animal strike can produce a $13,000 estimate, insurers have to assume a meaningful share of these cars will be write-offs, and everyone in that risk pool pays for it.
Is it fair, or is the reputation overblown?
It’s mostly fair, but the picture is not all bad, and it is not the same across every EV. The insurance penalty is heavily concentrated in Teslas and a handful of high-value models. Move to a different EV and the number can drop a lot.
One owner who cycled through two Teslas and then bought other electric cars, a Chevy Bolt and a Hyundai Ioniq 6, put it plainly:
“Insurance also went down with each purchase”
Every time they moved away from Tesla, the premium fell. Their comment is on r/electricvehicles. That is the most useful thing in this whole post if you are still deciding what to buy: the brand and model on the quote sheet is a lever you can pull before you ever sign anything.
How to lower EV insurance
You have more control than the first quote suggests. Some of these you do before you buy, some at renewal, and a few of them are worth real money.
- Get quotes before you buy, and before you pick a trim. Run the exact year, model, and trim through two or three carriers first. The number should help decide the purchase, not surprise you after it.
- Compare non-Tesla EVs. As that owner found moving to a Bolt and an Ioniq 6, premiums on other EVs can be dramatically lower for similar range and features.
- Raise your deductible. Going from a low deductible to a higher one lowers your monthly premium. Just keep the deductible to something you could actually cover if you had a claim.
- Bundle home and auto. Putting your homeowners or renters policy with the same carrier usually knocks a chunk off both.
- Ask about EV or usage-based discounts. Some carriers offer EV-specific or low-mileage and telematics programs that reward how you actually drive.
- Check the model’s total-loss and theft record. A model with a worse loss or theft history costs more to insure. Look it up before you commit.
- Compare Tesla’s own insurance against third parties. In some states Tesla Insurance undercuts the big carriers on Teslas, in others it does not. Get both.
- Use garaging and low-mileage discounts. Parking in a garage and driving fewer annual miles both lower the number, so make sure the quote reflects your real situation.
The single biggest move, though, is shopping carriers hard. That Washington driver saw State Farm and Geico quote the same Model 3 hundreds of dollars a month apart. Nobody should pay the higher figure without checking the lower one.
Frequently asked questions
Why is EV insurance so expensive compared to a gas car?
EVs cost more to buy and more to repair, mostly because of the battery pack and the sensors packed into the body. When a moderate crash pushes the repair estimate high enough, insurers total the car instead of fixing it, and that higher loss risk shows up in your premium.
Why is Tesla insurance so expensive specifically?
Teslas combine high vehicle values, limited certified body shops, pricey parts, and in some cases worse loss histories. Kelley Blue Book has reported Tesla insurance costs rising fast, and owner quotes back that up. Other EV brands often insure for noticeably less.
Is a used Tesla cheaper to insure than a new one?
Not always. One owner found a used 2023 Model Y quoted higher than a new 2025 on the same policy. Newer cars can carry safety and repair advantages that insurers reward, so always compare the specific years side by side.
Does switching to a non-Tesla EV really lower my premium?
Often yes. One owner reported their insurance went down with each move away from Tesla, toward a Bolt and an Ioniq 6. Run quotes on a few different EVs before you buy, because the model you choose is one of the biggest factors in the price.
What is the fastest way to lower an EV insurance quote?
Shop at least three carriers, then raise your deductible and bundle home and auto. Those three moves alone can cut hundreds off the same coverage, since carriers price the same car very differently.
Trey Linder writes about EVs, home batteries, and rooftop solar for homeowners at Electrified Experts.